
Original figure, explained in English
Responses to Common Objections.
The full-day Start-up Valuation seminar, organised with the EACVA, recently took place in Vienna for the third time. It was fully booked, with 16 participants, all experienced valuation professionals. The subject clearly attracts considerable interest in the valuation community and reflects current developments.
It is also a complex subject. Few other areas bring the ‘old’ valuation world, whose foundations remain sound, into such direct contact with new circumstances that challenge familiar ways of thinking. It is therefore unsurprising that participants have raised many questions and objections. There has been no shortage of stimulating discussion. This has helped me clarify my own thinking and present some aspects differently. Below, I address a selection of questions and objections from earlier seminars.
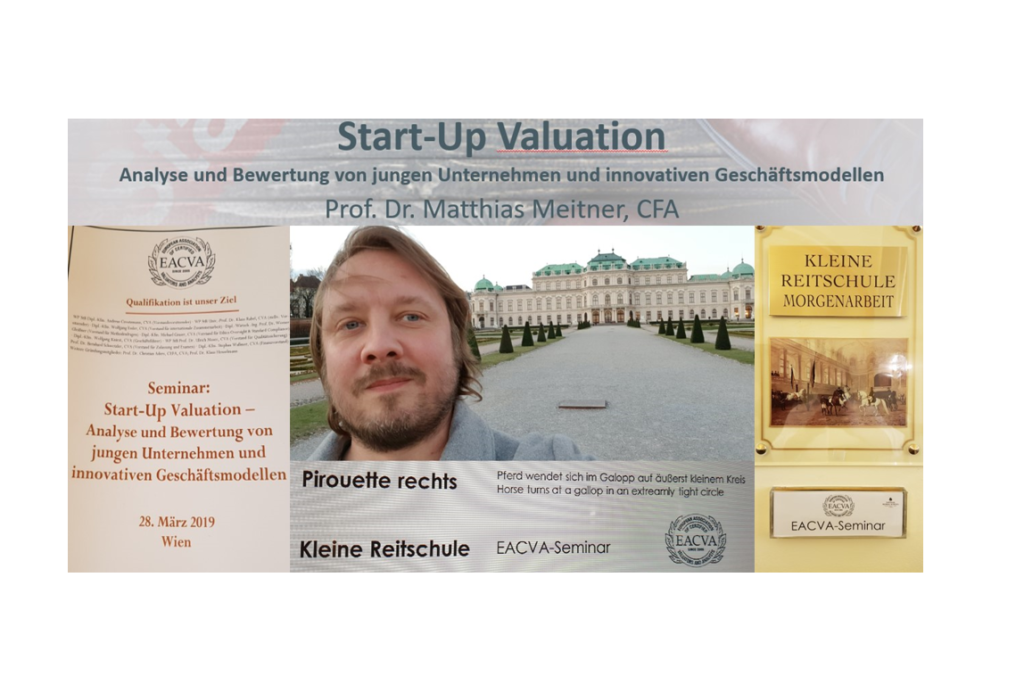
Original figure, explained in English
EACVA seminar: Start-up Valuation, Analysis and Valuation of Young Companies and Innovative Business Models, taught by Professor Matthias Meitner, CFA, in Vienna on 28 March 2019. The pictured venue is the Kleine Reitschule, or Small Riding School. The equestrian slide describes a right pirouette, in which a horse turns at a gallop in an extremely tight circle.
- Can Start-ups Be Valued at All? There Is So Much Uncertainty!
Of course they can. But uncertainty must be handled with great care. Knowing relatively little does not mean knowing nothing. In most cases, however, a start-up’s value is better expressed as a range than as a point estimate. Sometimes, though not always, that range is quite wide. It still supports decision-making, particularly in a world where even many professional investors pay little attention to valuation ranges and prefer to follow the market.
Two points apply. First, seemingly unmanageable uncertainty often, though unfortunately not always, becomes much more tractable after deeper fundamental analysis. Second, if uncertainty can be translated into terms we can work with, a sound general understanding of business valuation can take us a long way.
- Discounted Cash Flow Is Unsuitable for Start-ups!
Yes and no. The DCF model as originally taught is probably unsuitable for valuing start-ups. Deriving discount rates from the Capital Asset Pricing Model (CAPM) will not work in most cases. Forecasting a single cash flow figure for each period of the detailed forecast and then discounting it will usually fail to capture the distribution and uncertainty of outcomes. The underlying logic nevertheless remains valid: a company’s value is the present value of its expected future cash flows. There are ways of applying that present-value perspective to start-ups.
- What Approaches Are Available?
One promising approach is to imagine the start-up at a more mature stage, perhaps five years after the valuation date. In that state, or more accurately those states, because several development paths are possible, the company becomes easier to value. We are moving closer to a valuation environment we know. We then need to discount those possible future states appropriately to the present. Of course, it is not quite that simple, and plenty of pitfalls remain. But this basic idea often makes the task considerably more manageable.
- What Discount Rate or Required Return Should I Use?
This is a very common question and rightly leads to lengthy discussions. There are rules of thumb, lessons from experience and analytical approaches. But the data available for young companies are often far less satisfactory than the capital market data used in the CAPM. The most promising approach is probably to separate business-model-specific risk from the imprecision of our forecasts. Experience suggests that the required return for the former can often be assessed within the range familiar from conventional valuation. The latter is then reflected in the valuation range. This technique allows even high-risk start-ups to be valued using the fundamental principles of present-value analysis.
- Management Can Tell You Anything…
Yes, and it often does. Founders also tend to speak a different language from valuers: more technical and less focused on risk. This reinforces the importance of analysing management and the team. What economic meaning lies behind management’s statements? ‘10% growth’ from an outspoken, aggressive manager may mean something different from the same claim by an introverted, analytical engineer. How should qualitative statements be converted into quantitative estimates? ‘Our competitors are far behind us in development’ might imply a small valuation advantage or an enormous one. And, of course, do particular management roles need strengthening to give the start-up the team it requires?
It is natural that founders often communicate less professionally than a typical DAX chief financial officer. Valuers have to work with that. Frankly, it can be an advantage: thoughtful follow-up questions may reveal considerably more valuation-relevant information than conversations with a large-company CFO trained in every aspect of corporate communication.
- As an Expert Valuer, I Must Determine a Single Euro Amount. Can That Be Done Meaningfully?
That is the difficult question, and a very legitimate one. I am an expert valuer myself. My answer is always that it must be possible, but I am far more comfortable with ranges. Point estimates in this setting inevitably cause some unease and require additional calibration.
- Can I Have an Excel Model Where I Enter the Figures and Get a Valuation?
A classic request. Unfortunately, it is not that simple. Start-up valuation is primarily an analytical exercise. The model should follow the analysis. Anyone unwilling or unable to undertake that analysis will struggle to value young companies meaningfully.